Part 4 of 6 · The Technology Behind Better Outcomes — a technical briefing series from Quill Direct Vet Care.
Pet insurance has a settlement problem, and it is not an actuarial one. The claim is submitted after the fact, by the owner, from a receipt, into a carrier process the clinic cannot see — and the owner floats the entire cost until it resolves. Quill collapses that sequence: coverage is validated before treatment, the claim is assembled from the clinical record rather than reconstructed from paper, and the money moves along a state machine and a double-entry ledger that both sides can inspect.
1. The structural defect in the current flow
Process flow · Illustrative
Conventional reimbursement
Visit; owner pays 100%
Owner finds receipt and files claim
Carrier requests records; clinic mails them
Adjudication
Reimbursement
Days to weeks of float carried by the owner
Quill direct care
Pre-visit coverage validation
Visit + ambient documentation
Estimate priced against the fee schedule
Owner sees the split up front.
Claim assembled from the clinical record
Submitted at checkout.
Adjudication with complete evidence on first pass
Owner pays only their share — float removed or absorbed
The pet insurance market is growing quickly — NAPHIA’s State of the Industry reporting, drawn from members representing 99% of North American policies in effect, tracks a steadily expanding insured-pet population and sustained double-digit annual growth in gross written premium. Growth of that speed makes the settlement defect more expensive every year, not less: more policies flowing through a reimbursement model that was designed around mailed receipts.
The defect has three distinct costs. The owner carries the full price of care at the moment of highest emotional stress. The clinic absorbs the collections risk and the records-request labor. The carrier adjudicates from a reconstructed narrative rather than the primary clinical record, which is why records requests exist at all.
2. The claim as a state machine
Quill does not treat claim status as a text field that services update opportunistically. It is a formal state machine with defined states and explicitly permitted transitions, implemented in code and covered by tests. An illegal transition is rejected, not logged and tolerated.
| Stage | Representative states | What is guaranteed |
|---|---|---|
| Pre-service | draft, coverage_validated, awaiting_visit | Eligibility and expected coverage are established before treatment begins, so the estimate the owner sees is real. |
| Submission | submitted, processing | The claim carries the clinical record, the itemized invoice, and the evidence attachments as one packet. |
| Adjudication | processing, information_requested, approved, denied | Every determination is attributable to a rule or reviewer, with the rationale retained. |
| Settlement | approved, paid, settled | Ledger entries post in balanced pairs; a payment cannot exist without its counterpart. |
| Exception | information_requested, disputed, cancelled | Exceptions route to a queue with an owner and an age, rather than disappearing into a status. |
Why a state machine is a commercial asset
Because transitions are explicit, every claim has a complete, ordered, timestamped history. That single property produces auditability for the carrier, real status visibility for the owner, cycle-time analytics for the practice, and a testable invariant for the engineering team.
It is also what makes exception handling tractable: an exception is a claim that has been in a state too long, which is a query — not an investigation.
3. Three payment paths, one transparent engine
Quill’s fee engine calculates every transaction through one tiered schedule, and it is deliberately legible. The fee is computed on the amount Quill is actually facilitating, tiered by transaction size, bounded by configured minimum and maximum, and — critically — disclosed to every party before anyone commits.
| Path | Mechanics | Who carries the float | Clinic receives |
|---|---|---|---|
| Direct Pay | The insurer-covered portion is paid to the clinic directly; the owner pays only their responsibility. | Insurer | Full service total |
| Quill Advance | Quill fronts the insurer-covered portion at the point of care and recovers it from the carrier. | Quill | Full service total |
| Owner Self-Pay | Uninsured or non-covered service, facilitated through the same rails. | Owner | Service total less fee |
Two properties of the engine matter more than the rates. First, the clinic receives the full service total on both insured paths — the practice is not financing the insurance industry’s processing time. Second, on facilitated paths the platform fee is split transparently rather than embedded in a spread, and the breakdown is rendered to the owner in the checkout flow. Fee schedules are configurable per practice and versioned, so a rate change is an auditable event rather than a silent repricing.
Worked example
A $1,200 procedure with $900 of insurer-covered benefit under Direct Pay: the owner’s responsibility is the $300 balance plus a disclosed share of the platform fee calculated on the $900 facilitated amount; the clinic receives the full $1,200; the carrier settles the $900 through the ledger. Every number in that sentence is visible to all three parties in the interface before the transaction is authorized.
4. The ledger
Money movement in Quill is recorded as double-entry accounting, not as status flags on a payments table. Every advance, recovery, fee, refund, and settlement posts as balanced entries against defined accounts.
-
Reconciliation is arithmetic. Carrier remittances reconcile against expected recovery amounts automatically; the exception queue holds only genuine mismatches.
-
Recovery is tracked as an asset. Quill Advance creates a receivable with an explicit aging profile, which is what makes the advance product underwritable rather than a hope.
-
Financial state is derived, never asserted. Balances are computed from entries. There is no field a bug can set to the wrong number.
-
Audit reconstruction is complete. Any balance at any historical moment can be rebuilt from the entry log, which is the baseline expectation of a SOC 2 examination.
-
Tenant isolation is enforced below the application. PostgreSQL row-level security policies scope financial records in the database engine, so an application-layer defect cannot expose another party’s ledger.
5. Meeting carriers on their own rails
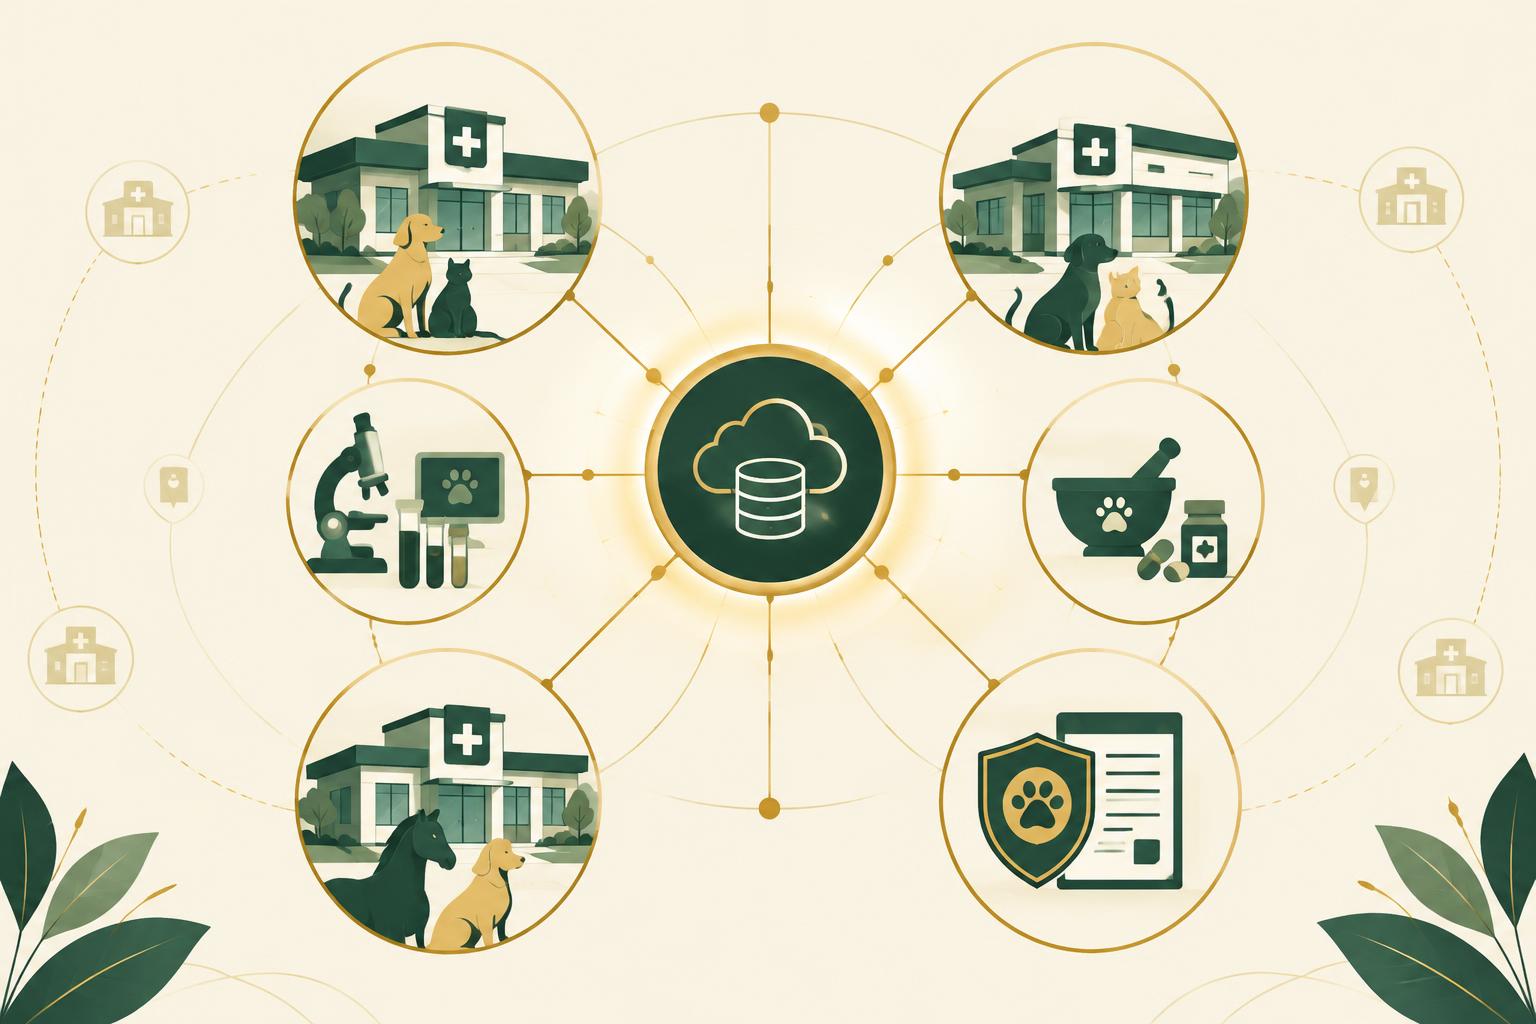
Quill does not require a carrier to adopt a new integration standard as the price of participation — a requirement that has killed more insurtech pilots than any technical failure. The exchange layer supports the protocols carriers actually run:
| Protocol | Typical carrier posture | Quill support |
|---|---|---|
| REST / JSON | Modern digital-native carriers and MGAs. | Native, with webhook callbacks for status transitions. |
| Webhooks | Event-driven status and remittance notification. | Signed, retried, and observable — with delivery metrics and a replay path. |
| EDI X12 (837 / 835 / 270 / 271) | Established carriers with mature clearinghouse infrastructure. | Claim submission, remittance advice, and eligibility inquiry mapped to the standard sets. |
| HL7 / FHIR R4 | Carriers and partners aligned to healthcare interoperability. | Resource-level mapping for clinical evidence exchange. |
| SFTP batch | Carriers operating scheduled batch reconciliation. | Scheduled drops and pickups with manifest validation. |
| ETL buckets | Analytics and bulk data-warehouse feeds. | Structured extracts on a defined cadence. |
Each pathway resolves into the same internal claim object and the same state machine. Protocol is an edge concern; the core is uniform. That is what allows Quill to onboard a carrier on the carrier’s timeline rather than on a platform migration timeline.
6. Integrity and exception handling
Faster settlement without integrity controls is just faster leakage. Quill pairs acceleration with detection:
-
Pre-service validation catches coverage problems before treatment, which eliminates the worst outcome in the system — a denial discovered after the owner has already been told they were covered.
-
Evidence at submission. Receipts and records are attached and OCR-extracted at the point of claim assembly, and the extracted values are cross-checked against the itemized invoice.
-
Pattern-level fraud signals operate across claims rather than within one, and each flag is delivered with the pattern and evidence that generated it so a human reviewer can adjudicate the flag itself.
-
Aged exception queues hold anything that stalls, with an owner and a clock, so no claim quietly ages out of anyone’s attention.
-
Immutable audit trail. Every state transition, review decision, and ledger posting is recorded with actor and timestamp, and the underlying database is deployed with zone-redundant high availability and point-in-time restore.
7. Why this is the hard part to copy
A competitor can build a claim submission form in a sprint. What takes years is the composite: a tested state machine that carriers will accept as authoritative, a configurable fee engine with disclosed economics, a double-entry ledger that survives an audit, six live exchange protocols so no carrier has to change to participate, and pre-service coverage validation wired into the clinical workflow that generates the claim in the first place.
Each layer is only valuable in the presence of the others. Coverage validation without clinical integration is a lookup tool. A ledger without settlement volume is a spreadsheet. Multi-protocol exchange without a normalized claim object is six brittle integrations. Assembled, they are a payments and adjudication network for a market growing at double-digit annual rates — and the participants on both sides are already on it.
Evidence base
The following peer-reviewed findings were verified against primary sources; full citations appear in the References section.
Cost governs the care a pet actually receives. Of 2,296 pet guardians surveyed, 1,924 (83.9%) agreed that the expense of veterinary care affects the level of healthcare their pets receive, while only about 36% considered pet insurance essential. (Awawdeh, Waran & Forrest, Animal Welfare, 2025)